
America’s Defense Industrial Base Begins at the Mine

Abstract
The U.S. defense industrial base depends not only on the factories that produce weapons, but also on the mines, refineries, supply chains, and corporate structures that provide their critical inputs. This article examines how China’s position in critical minerals creates strategic dependencies for the United States, focusing on cobalt, copper, rare earth elements, and other materials essential to defense production. It argues that supply-chain security cannot be assessed solely by the geographic location of mines or refineries. Ownership, financing, governance rights, offtake agreements, and the potential for future changes in corporate control can also shape who ultimately influences strategically important assets. Drawing on several recent cases, the article illustrates how these vulnerabilities can affect U.S. supply-chain security, and outlines a strategy combining domestic production with allied supply chains and government-backed financing.
Confronted by significant bottlenecks, the U.S. faces a sobering reality: The military power that has for so long underpinned its global leadership only obtains its robustness insofar as the defense industrial base is capable of replenishing it.
One notable vulnerability arises in the procurement of aircraft parts, missiles, drones, radars, satellites, precision-guided systems, batteries, and communications networks. These necessary components of the military supply chain have a strict reliance on critical raw materials that are concentrated in a few localities around the globe, and are difficult to substitute. Turning traditional strategic considerations in the defense industry upside down, an adversary may no longer have to defeat superior American weapons systems to gain victory. Disrupting the supply chains in service of the U.S.’s defense industrial base – potentially at as early a stage as extraction – would prove sufficient.
This is something that China has understood for years. The best evidence for this is its robust mining, processing and refining infrastructure, which Beijing has supplemented with reliable sourcing partnerships and other minerals projects abroad. China controls between 60% and 90% of the production of most key materials essential for defense, renewable energy and modern computer technology worldwide. This advantage is not simply the result of competitiveness, but emerged in large part due to the symbiotic relationship between China’s state-capital system, its industrial leaders and its national strategic objectives.
The lesson for Washington should be clear: access to resources is just as critical as securing the industrial capacity and corporate structures that are capable of turning those resources into the strategic capabilities the U.S. military relies on.
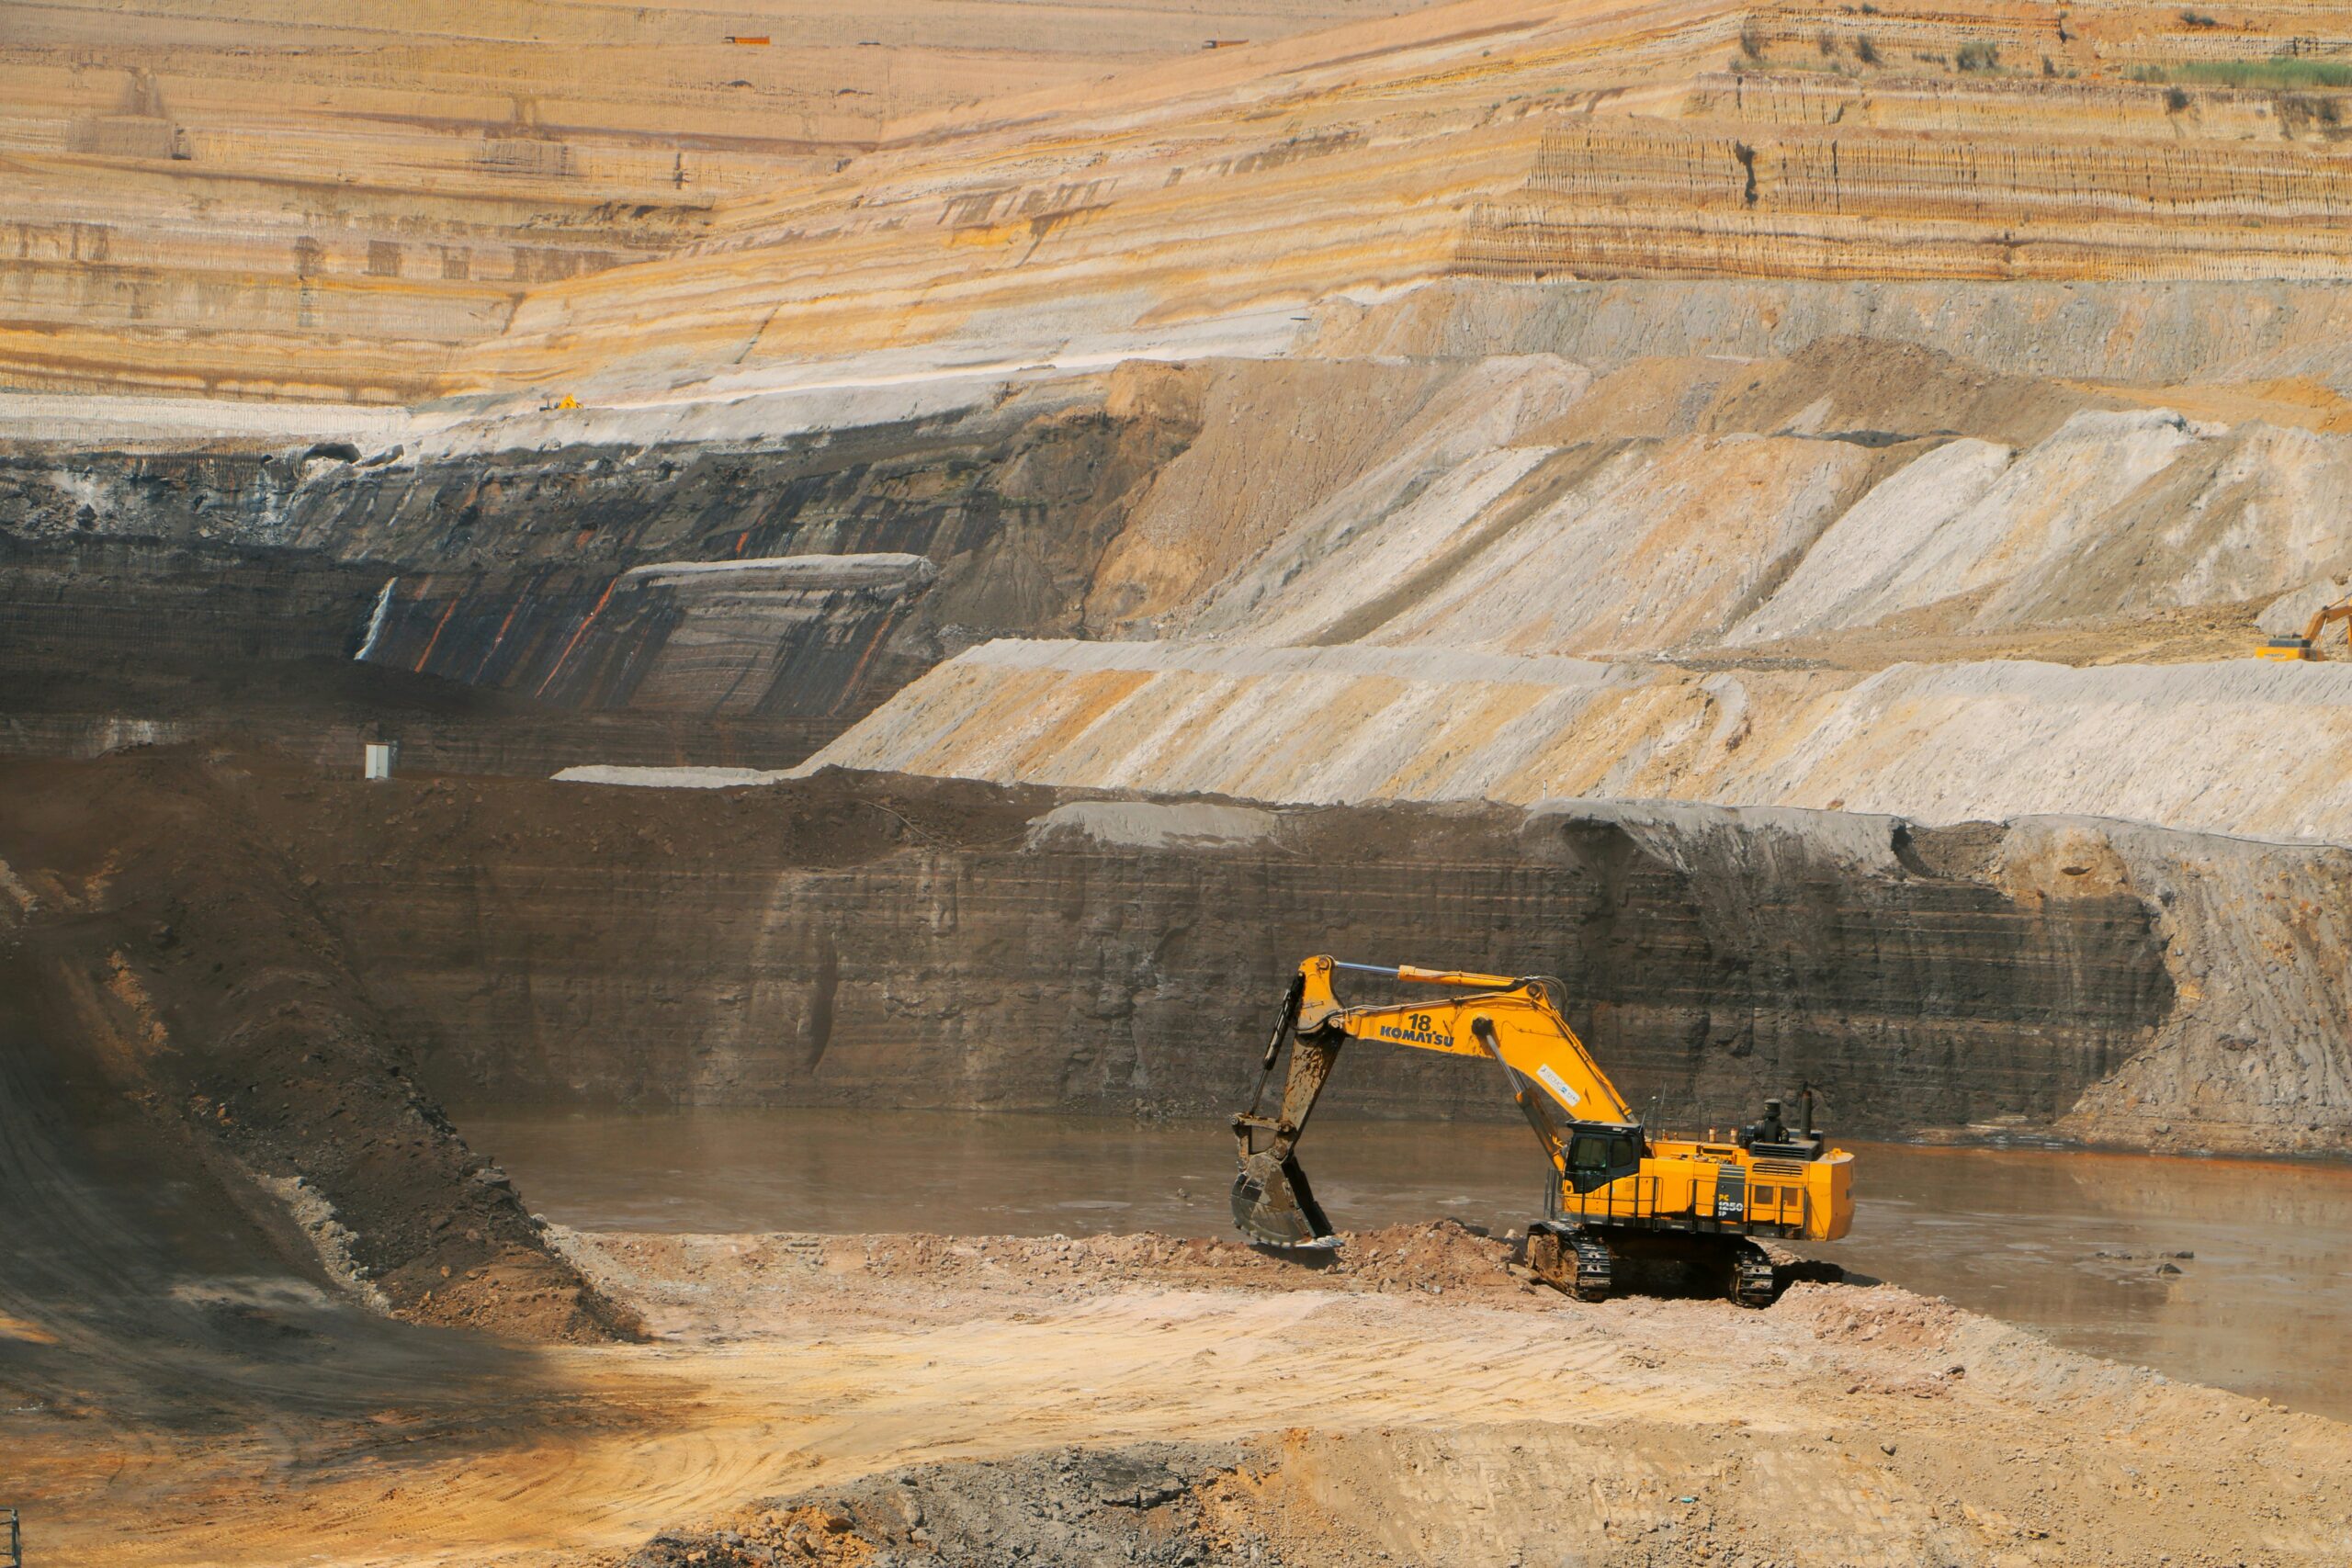
A good example of securing a controlling interest in both mining and refining in the cobalt and copper supply chains is provided by the commercial relationship between China and the Democratic Republic of Congo. On one side of the relationship, CMOC Group Limited (formerly called China Molybdenum) acquired an 80% ownership stake in the DRC’s Tenke Fungurume Mining copper-cobalt project, which makes up roughly 38% of global cobalt production. Simultaneously, on China’s side, significant processing capabilities were developed at home. China now refines more than 79% of the world’s cobalt.
This one supply chain alone creates significant dependencies for the U.S. in a number of strategic sectors. Cobalt is used in the production of lithium-ion batteries that power electric vehicles, drones and other energy-storage systems. It is also an integral part of the superalloys used in jet engines and other high-performance aerospace applications. Disruption to cobalt supplies in the defense sector in particular would negatively impact the production of batteries, aircraft engines, missiles and other military systems that depend on these materials.
While Washington has increasingly tried to expand its domestic mining and refining capabilities, and worked with allies including Japan, Australia and South Korea to build “friend-shored” supply chains diversified away from China, another challenge is the ownership and control structures of strategically important companies.
A characteristic of modern capital markets has made national security screening more difficult. U.S. mechanisms are generally adept at asking whether a strategic asset is controlled by China, but less experienced in uncovering private-equity structures, financing by multiple institutional investors, and the consequential differences between ownership and control over the operations of firms. The absence of apparent direct Chinese ownership no longer guarantees the lack of Chinese influence in a trade or joint venture relationship.
The attempted acquisition of Lattice Semiconductor illustrates this risk. In 2016, U.S.-based private equity fund Canyon Bridge agreed to acquire the U.S. chipmaker for $1.3 billion. Its sole investor was a unit of China Venture Capital Fund, whose funding was ultimately traced to China’s State Council. In September 2017, President Trump blocked the deal following a CFIUS recommendation, citing the Chinese government’s role in the transaction and the potential transfer of semiconductor technology.
The recent and ongoing battle of corporate control over Korea Zinc may be another example. Korea Zinc produces strategically important minerals including zinc, lead, copper, and a range of other non-ferrous and strategic metals, including indium, bismuth, and antimony.
To strengthen American critical minerals supply, the U.S. government and Korea Zinc formed a joint venture under the name Crucible Zinc Inc., specifically to decrease America’s reliance on Chinese refining. The Department of Defense took a significant stake in the $7.4 billion smelter project in Tennessee, and the federal government also backed the project with a direct grant under the CHIPS and Science Act.
While Washington and Korea Zinc’s leadership under Chairman Choi are trying to build a more resilient Western and allied supply chain, the company has become embroiled in a prolonged battle for control. The Young Poong Group and the Jang family that leads it have maintained a shared governance model with the Chois for decades – an agreement that collapsed only in recent years. This may have been an opening for China. In 2024, Young Poong officially partnered with private equity firm MBK Partners and launched a bid for Korea Zinc shares.
MBK Partners’ explicit focus on the Chinese market and their history of mutual investments – with MBK acquiring China’s largest car rental firm, CAR Inc. and China’s sovereign wealth fund, the China Investment Corporation contributing to MBK’s sixth buyout fund – deserve scrutiny.
As part of the broader control battle, the MBK-Young Poong alliance has been presenting itself as America’s operational partner for Crucible after unsuccessfully opposing the project in the Korean court on the grounds that it puts Korea’s national core technology under U.S. influence. The Crucible JV holds a 10% stake in Korea Zinc that currently supports the incumbent management; securing that stake’s support would significantly boost the alliance’s takeover attempt.
Thus, in the context of Korea Zinc’s control, Washington should carefully examine the financial and corporate networks that can determine who supplies capital, owns governance rights and makes decisions in the future, especially when these maintain direct connections to the Chinese government and Chinese state capital.
The defense industry’s reliance on rare earth mining far exceeds only Korea Zinc’s promised importance in the refining of gallium, germanium, and antimony. Rare Earth Elements (REEs) are also essential components of virtually all defense-related products. The transaction between China’s Shenghe Resources, Australia’s Peak Rare Earths and the Ngualla project in Tanzania presents a case in which a single mining deal could lock up the operations of an entire critical mineral supply chain from mine to market. Shenghe has become Peak’s largest shareholder with a nearly 20% stake in the company while also securing a 100% offtake agreement for all rare earths produced at Ngualla. This strategic positioning has essentially created a fully integrated, China-centric pipeline for the production of certain REEs.
China’s success in critical minerals demonstrates that supply chain security cannot be measured by where a mine or refinery is located. A resource deposit in an allied country can still feed a China-centric supply chain if Chinese firms control the offtake, processing, financing or key corporate decisions. Similar restrictions may arise from a refinery being built on American soil. Washington therefore needs to complement its push for domestic production and “friend-shoring” with a more rigorous concept of trusted control. This approach could examine ultimate beneficial ownership, financing, governance rights, offtake agreements and the possibility of future changes in control. Shutting out allied or private capital is not necessary, but it requires attention paid to who has the ability to influence the assets which American military power depends on. The defense industrial base does not begin at the weapons factory. It reaches back to the refinery, the mine and, increasingly, the shareholder register.
A more resilient strategy would see a strategic combination of reliable domestic production, coupled with a network of allied supply chains. Australia, Canada and the United Kingdom are all partners with access to vast mining resources alongside processing and refining knowledge. Continued support from government-backed financing and long-term offtake agreements would facilitate the creation of strategic stockpiles, giving producers a certainty they sorely lack today, and allowing them to develop projects which they otherwise would not be able to manifest in competition with Chinese-backed capital.
Washington has a range of issues which it must also address at home, including the impact of lengthy permitting delays, high capital costs and limited downstream processing capacity. Enabling the production of more minerals is an easy policy solution to argue for, however the United States needs to build alternative capacity across the entire chain. The tremendous scope of American defense procurement would guarantee ongoing demand for strategically important materials. This could potentially create a a supply chain in where no single foreign government or company could control the critical link between mine and military product. Friend-shoring is thus an integral part of this process. “Friendly” however, means more than simply the flag under which a mine or refinery operates; we must also account for who owns the asset, who finances it, who controls its output. This necessarily impacts who has the ability to disrupt the supply chain.


